Identity verification guide
Clubhouse Casino KYC Australia: Verification Documents and Withdrawal Checks
 Available in US
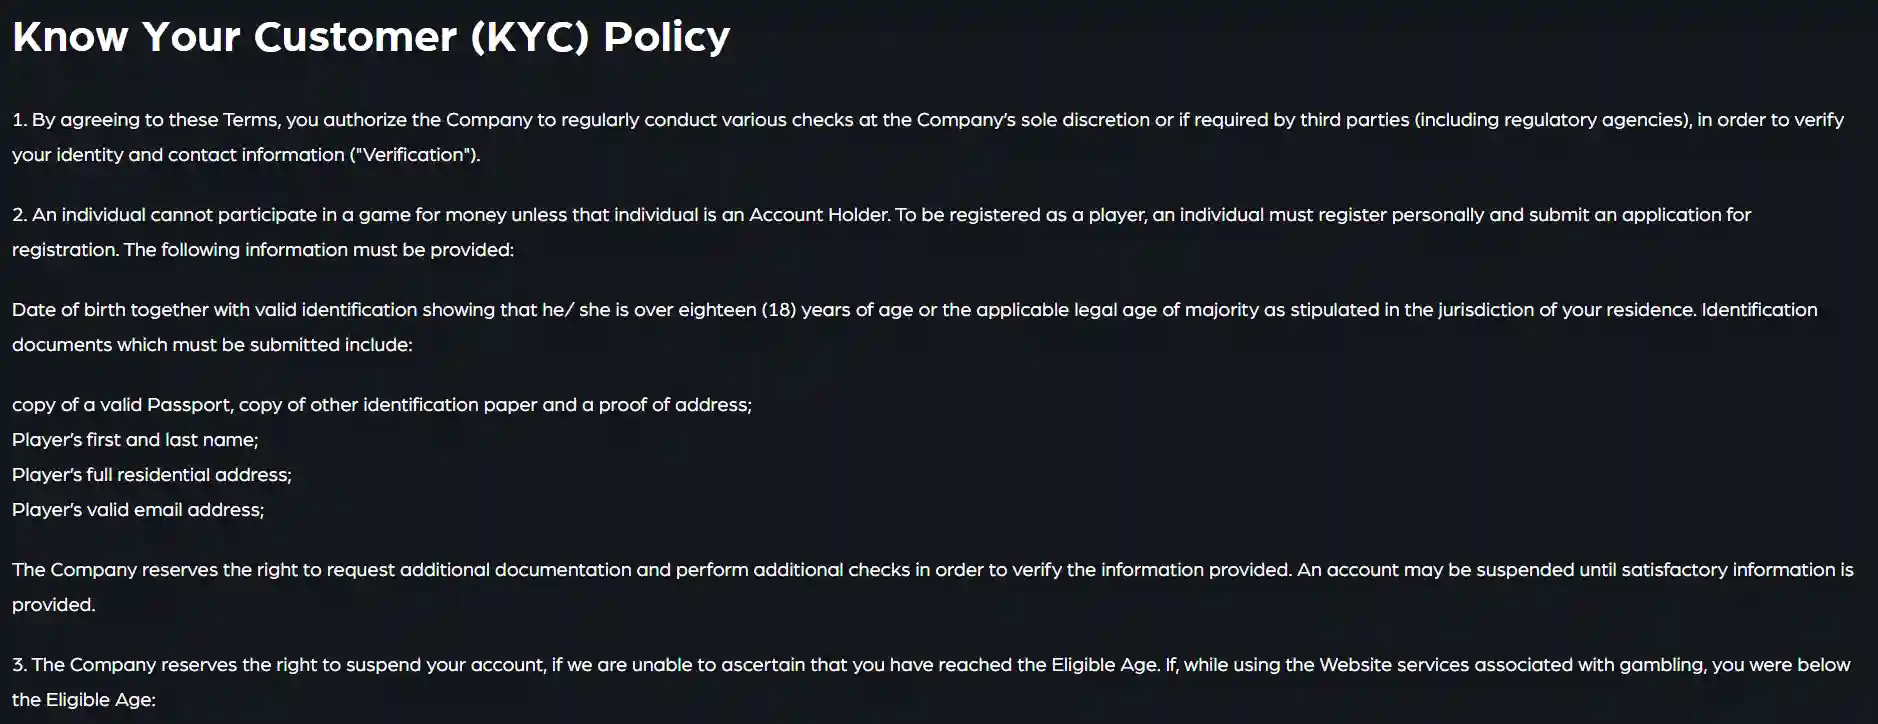
Clubhouse’s current KYC Policy and terms describe the main evidence categories used for verification: government-issued identification, proof of address and, when requested, evidence connected to the payment method. The terms also allow additional phone verification and specify video verification in particular circumstances. The current KYC Policy states that consideration of KYC documents can take up to 30 working days from the point when the client has provided all requested documents. That is a published maximum consideration window, not a promise that every check will take 30 days. Verification is also relevant to withdrawals because a request can remain pending until required checks are completed.
Table of Contents
- What documents Clubhouse can request
- Identity evidence and payment ownership should match
- Additional phone and video checks
- How KYC interacts with a withdrawal
- The two-week clauses and the 30-working-day KYC window describe different events
- Documents the operator can request versus documents every user will submit
- What to do before the first withdrawal
- KYC and regulatory status are separate
- KYC is not necessarily a one-time account event
- KYC details that vary by account
- Prepare for KYC before a withdrawal depends on it
What documents Clubhouse can request
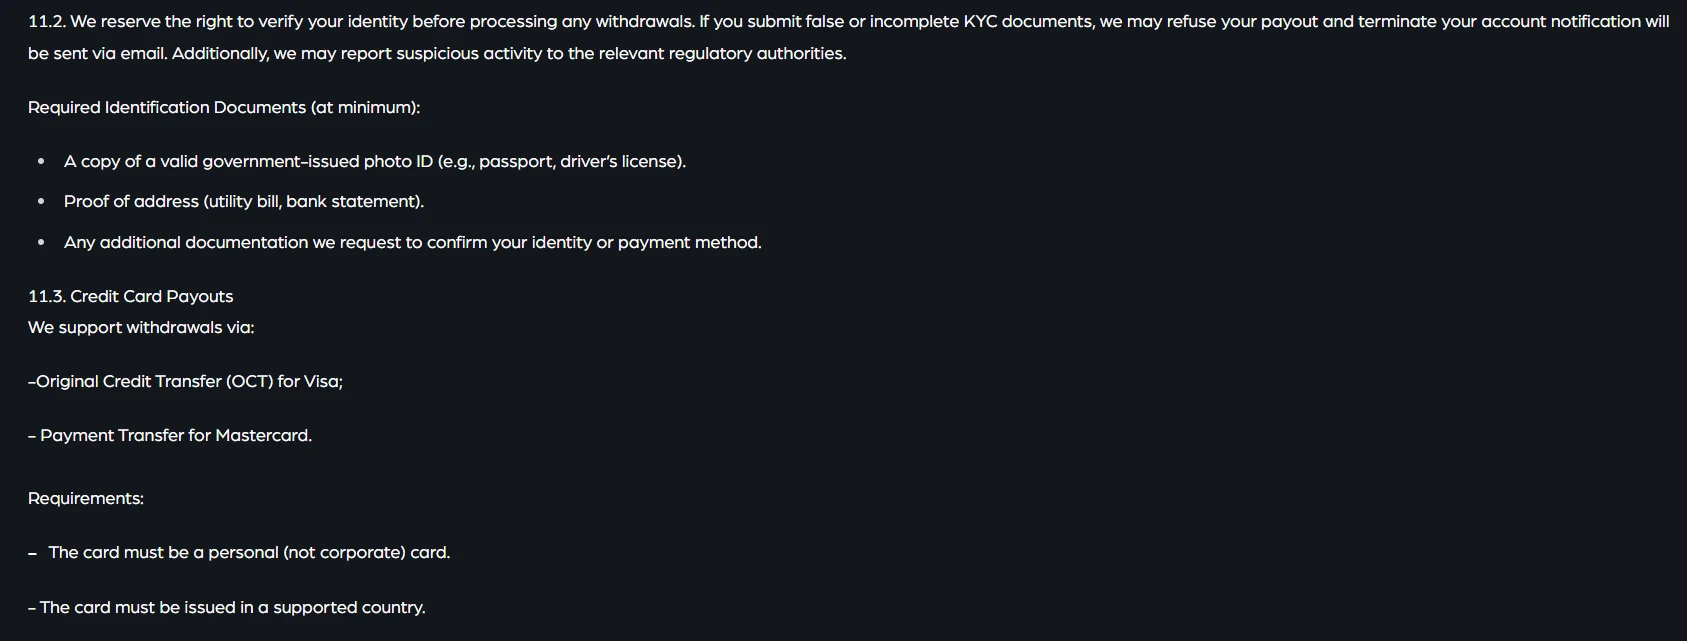
The current official terms identify the following document categories for identity verification:
- Government-issued photo ID. The terms give passport and driver’s licence as examples.
- Proof of address. The terms give a utility bill or bank statement as examples.
- Proof of payment method when requested. The terms give card front/back evidence or an image of the e-wallet account as examples.
These categories are more useful than a generic statement that “KYC is required” because they show the types of documents that can be requested. The exact request can still differ by user and by the reason a check is opened, so not every player should assume that all categories will always be requested at registration.
The current terms also contain a withdrawal section that again names a valid government-issued photo ID, proof of address and additional documentation used to confirm identity or a payment method. That repetition reinforces the connection between account identity and payout review.
Identity evidence and payment ownership should match
Clubhouse’s terms require deposits to come from a bank account, card, e-wallet or other payment account registered in the player’s own name. That rule matters when proof of payment method is requested. A KYC check is easier to understand when the account holder, the identity document and the funding source all refer to the same person.
Practical preparation does not require guessing what file type the operator will accept. Keep current, legible identity and address evidence available, and make sure the payment method belongs to the same account holder. Follow the actual upload or support instructions displayed in the account when a request is made rather than relying on an old third-party file-format list.
Preparation principle
Consistency is more important than over-collecting documents. Use accurate account details, payment methods in your own name and current documents that match those details.
Additional phone and video checks
The official terms allow a live phone verification in addition to document checks. They also state that video verification can be required in a specified circumstance involving documents that cannot be provided in the requested scripts. These are conditional checks, not evidence that every Clubhouse customer must complete a call or video session.
Verification can be layered rather than identical for every account. Core identity and address evidence are the main categories, proof of payment method can be added when needed, and additional phone or video verification can form part of additional checks.
If the operator requests an additional check, use the contact and account route presented by Clubhouse. Do not send identity material to addresses or upload links copied from an unaffiliated website or social post.
How KYC interacts with a withdrawal
The current terms say withdrawal requests remain pending until required verification steps are completed. They also reserve the right to verify identity before processing withdrawals. This means the visible time between clicking withdraw and receiving funds can contain more than one stage.
- Withdrawal request. The player submits the request subject to the account and payment rules.
- Verification review where required. The operator can hold the request while requested KYC is outstanding.
- Approval. Approval is a separate milestone from submission.
- Operator processing and payment-rail settlement. The terms state an aim to process withdrawal requests within 72 hours of approval, while the final payout timing can depend on the method and verification status.
The current AU terms also state a 30 AUD minimum fiat withdrawal. Those payout mechanics belong in the dedicated Clubhouse withdrawals guide, where the minimum, approval timing and method display times are evaluated together. On this KYC page, the important point is that verification can occur before the withdrawal reaches its normal processing stage.
The two-week clauses and the 30-working-day KYC window describe different events
The terms contain two-week clauses tied to failure to complete verification or failure to respond to contact attempts. One account section says that if the casino cannot reach a user by phone or email within two weeks of a withdrawal request, the account can be locked and the withdrawal cancelled. Another anti-fraud clause describes account termination if verification is not passed within two weeks of a request.
The two-week clauses describe consequences when required verification is not completed or contact attempts fail. They are not the same as the KYC Policy’s separate statement that consideration of submitted documents can take up to 30 working days after all requested documents are provided. Neither figure should be presented as a guaranteed routine approval time.
The distinction matters when a review is underway: one time reference concerns document consideration after the requested material has been supplied, while the two-week language concerns non-completion or failed contact. Account-specific requests and messages remain the best guide to what is still outstanding.
Documents the operator can request versus documents every user will submit
| Document or check | Current policy position | How to interpret it |
|---|---|---|
| Government photo ID | Listed in current official terms | Core identity evidence the operator can require |
| Proof of address | Listed in current official terms | Core address evidence the operator can require |
| Proof of payment method | Listed when requested or as additional evidence | Relevant when payment ownership or transaction checks need confirmation |
| Phone verification | Allowed as an additional check | Conditional, not universal |
| Video verification | Specified for particular document-script circumstances | Conditional, not universal |
| KYC document consideration | Up to 30 working days after all requested documents are provided | Published maximum consideration window, not a guaranteed completion time |
The table groups the main document and verification categories. The actual request presented to an account should control what the player sends.
What to do before the first withdrawal
- Review the account details. Names and address information should be accurate and consistent with the documents you hold.
- Use payment methods in your own name. The operator’s terms prohibit third-party deposits.
- Keep a current photo ID available. Government-issued photo identification is a sourced KYC category.
- Keep recent address evidence available. Proof of address is also listed in the current policy.
- Wait for the operator’s actual request. Do not send extra sensitive material to an unverified destination unless the operator requests it through an official channel.
- Respond to genuine verification contact promptly. The terms attach account and withdrawal consequences to prolonged non-completion or failed contact.
If you are still at the registration stage, return to the Clubhouse account and sign-up guide. It covers the one-account rule, login entry points, eligibility and the separation between operator access signals and Australian law.
KYC and regulatory status are separate
KYC is an operator account-control process, not a regulatory approval. The separate Australian regulatory position is covered in the Clubhouse licence and safety guide.
For verification purposes, the practical lesson is that a successful identity check answers an account question, not a local-licence question. Passing KYC confirms account requirements only; regulatory status is addressed separately.
KYC is not necessarily a one-time account event
The current Clubhouse KYC policy authorizes identity and contact checks to be conducted again at the operator’s discretion or when required by third parties or regulators. That matters because a successful earlier check should not be presented as a lifetime guarantee that the account will never be reviewed again.
A later request can arise in a different account context, including a withdrawal or a need to confirm identity and payment ownership. The safest preparation is therefore to keep the account details accurate over time and retain access to current documents that match those details. This is more reliable than assuming an old approval permanently closes the verification question.
The operator does not publish a fixed trigger schedule for repeat verification. The policy allows further checks, so a successful earlier review should not be treated as a lifetime guarantee that the account will never be reviewed again.
KYC details that vary by account
- No promise that verification is completed in a fixed number of hours or days.
- No claim that every player submits every possible document category.
- No promise that verification is permanent or can never be requested again.
- Accepted file formats, image dimensions and upload limits depend on the current account instructions.
- No claim that a passed KYC check guarantees withdrawal approval.
- No duplication of the full withdrawal-limit and method-timing table.
File formats, document freshness rules and case-specific upload instructions can differ by request. Follow the current instructions displayed in the account or provided through the operator’s official support channel.
Prepare for KYC before a withdrawal depends on it
Clubhouse KYC is best understood as a request-driven identity and payment-ownership check that can directly affect withdrawals. Core document categories include government-issued photo ID, proof of address and proof of the payment method when requested. Additional phone verification can be used, and video verification is specified in particular circumstances. A withdrawal can remain pending until required checks are complete.
Prepare by keeping account information accurate, using payment methods in your own name and retaining current, legible identity and address evidence. Do not interpret the two-week enforcement clauses as a routine KYC processing promise. For the current wording, consult the official Clubhouse terms and Clubhouse KYC policy.
For the wider context, see the Clubhouse Casino Australia review.
Published by the Clubhouse Casino team.